Greetings!
With the midterm elections behind us and the holidays just ahead, this week’s Advice for the Good Life is about navigating change, protecting what matters, and remembering the value of a good plan.
In Wealth Advisory, we explore how voter resistance to AI data centers is creating new uncertainty for technology stocks—and why keeping a long-term perspective matters more than ever.
In Wellness Navigator, Christine Despres reminds us that our brains deserve the same thoughtful attention we give our financial portfolios. She also introduces her upcoming 5-Day Brain Fog Reset, designed to help you begin the new year with greater clarity, energy, and focus.
And in our Parting Thought, a timely reminder that worry, much like debt, can exact a price—even when nothing is owed.
As always, I hope you’ll find something worth considering, putting into practice, or sharing with someone you care about.
Enjoy, and thanks for reading!
What Midterm Election Results Mean for Data Centers and Tech Volatility
In the days since the midterm election, stock markets have moved sharply in both directions, with technology and AI-related stocks at the center of the turbulence. One of the most closely watched issues for financial markets has been the outlook for data center construction.
Data center construction has served as a meaningful engine of economic activity and corporate profits, as businesses establish the infrastructure required to support AI applications. The midterm election results, along with related ballot measures, indicate that voters broadly favor placing restrictions on this type of construction at multiple levels of government.
These developments add to existing pressures on technology stocks. While this segment of the market has contributed meaningfully to portfolio returns in recent years, it also faces ongoing questions about valuations, interest rates, and whether large-scale AI infrastructure investments will ultimately deliver returns. That said, volatility in this area is not uncommon, and performance over longer time horizons has remained strong. Understanding what the latest election results mean for markets, and how investors can keep a broader perspective, is worth exploring.
Voters largely sought to restrict data centers
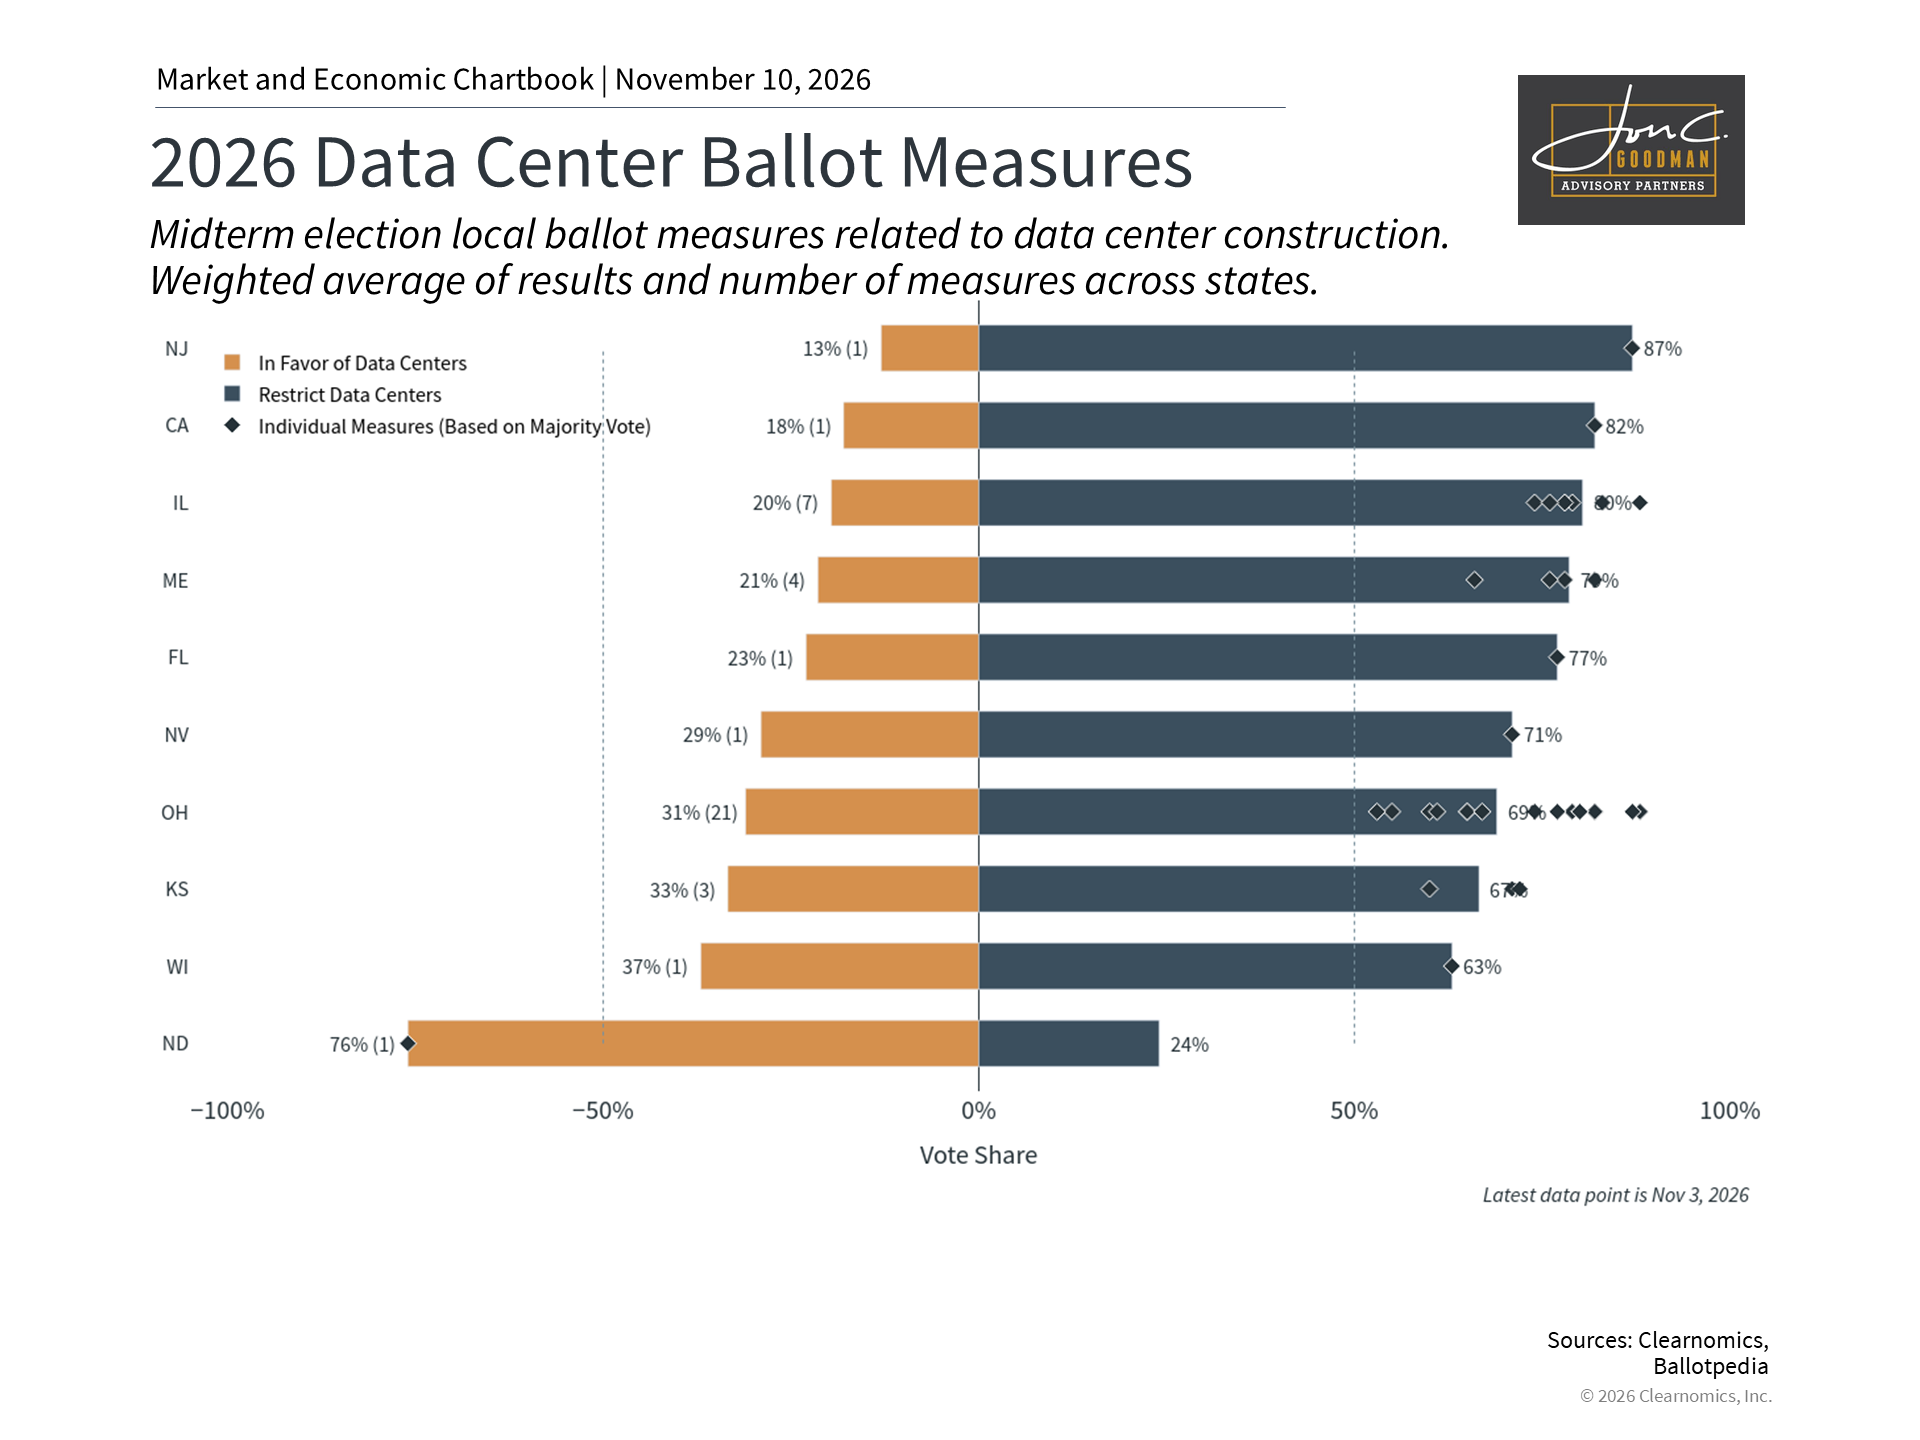
As the accompanying chart shows, voter opposition to data center construction was widespread. So far this year, there have been 47 local measures directly related to data centers, with 41 voted on during the midterm election across ten states.1 The ballot results indicate that voters support restrictions on data center construction by wide margins, with only one exception.
These measures varied considerably in scope, addressing zoning requirements, electricity and water usage, and rules specific to data centers. For example, one measure in Kansas banned “high-impact” data centers, defined as facilities using more than 10 megawatts of electricity or 100,000 gallons of water per day, for 10 years. Towns in New Hampshire and Maine approved temporary moratoriums on new construction.
The single exception in the latest election was Harwood, North Dakota, a town of roughly 850 people, where about three-quarters of voters rejected stricter review requirements on large industrial projects. That outcome clears the way for construction to continue on a $3 billion data center campus. The reported reason was that a data center would likely have been built nearby regardless of how residents voted. By allowing it within town limits, the community could capture tax revenues and other economic benefits.
The tension between large-scale infrastructure construction and the needs of local communities is not new, but it is intensifying as the demands of AI applications grow rapidly.
Historical parallels exist in the construction of oil and gas drilling sites, which communities have long evaluated by weighing environmental and quality-of-life concerns against jobs and tax revenues. The same “Not In My Backyard” (NIMBY) dynamic has also played out with highways, power plants, cell phone towers, and similar projects. Data centers represent the latest example of a large industrial buildout affecting residential communities, raising concerns about power usage, water consumption, and facility scale.
Another parallel is the construction of large, job-creating factories, which many towns and cities historically competed to attract. An extreme version of this was seen in the industrial towns of the 19th and 20th centuries, where manufacturing plants, mills, and production lines were not just central to local economies but had entire communities built around them. In many cases, these facilities brought real economic benefits, including jobs, tax revenues, and local investment. Looking back, however, these towns had a mixed track record, and history shows that heavy dependence on a single economic engine can create challenges, alongside concerns such as environmental degradation, noise, and strain on local infrastructure.
Data centers are following a similar pattern, with one key difference: they tend to be capital intensive, requiring substantial investment and equipment, but are not necessarily labor intensive. The fact that data centers may not represent a significant long-term source of local employment appears to be an important reason for the community resistance that ballot results have reflected.
Data center construction has supported the economy
Understanding why data centers have become such a focal point begins with understanding what they are. When a user visits a website or app, uses a search engine, sends an email, makes an online purchase, or interacts with an AI model, those requests are processed by servers. A data center is essentially a very large warehouse packed from floor to ceiling with servers, and can span anywhere from a few dozen to 1,000 acres. These servers operate continuously, requiring electricity, cooling, security, and more. Together, they form the physical infrastructure that underpins all digital services, a role increasingly shaped by AI usage.
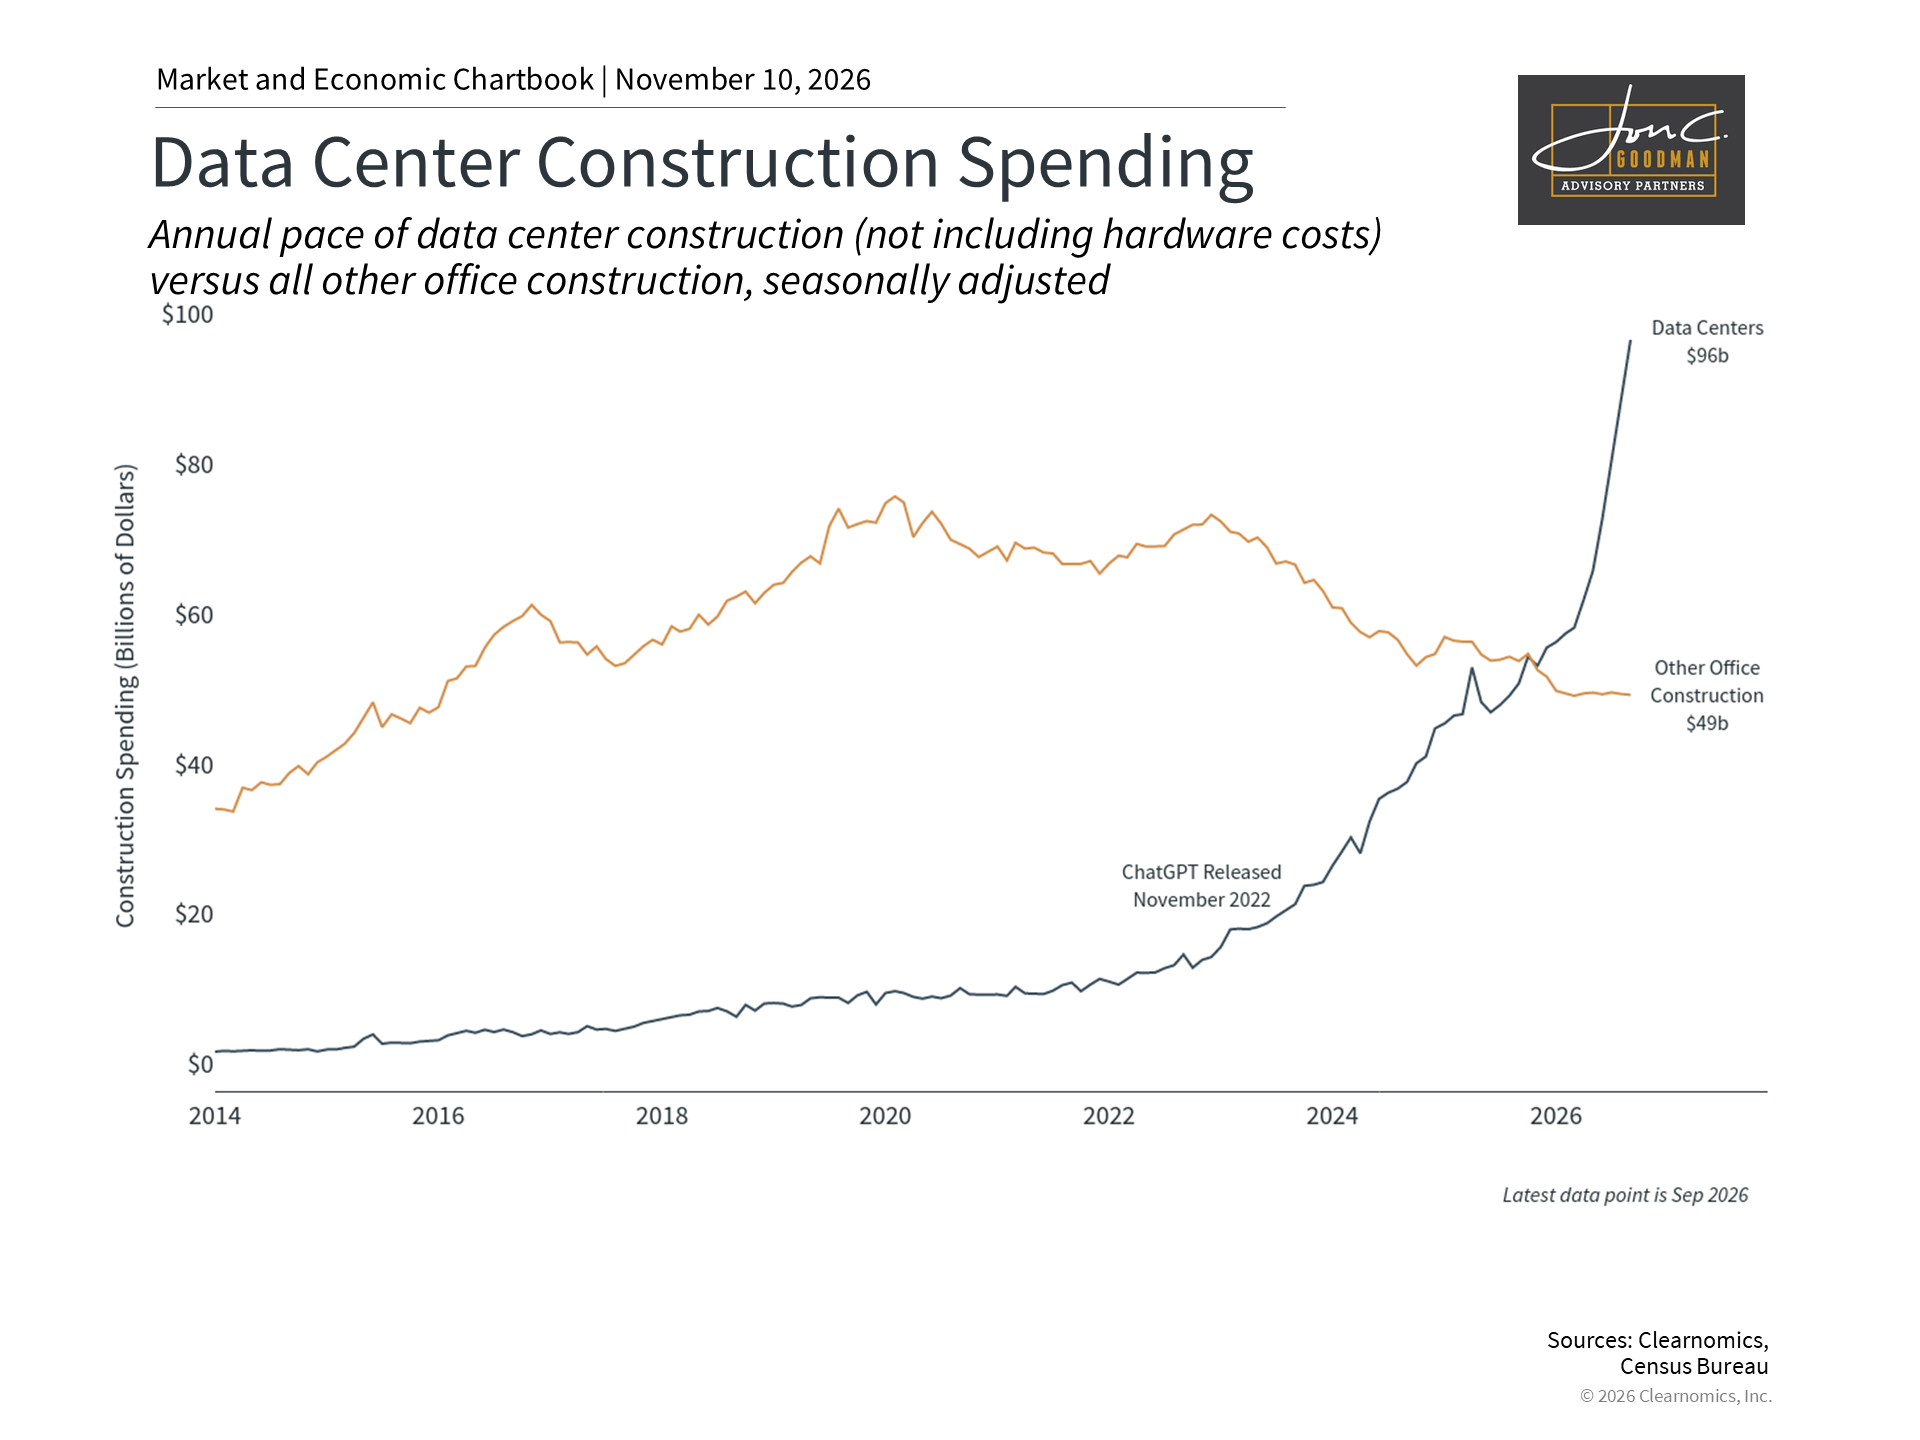
Spending on these facilities has grown substantially in terms of its contribution to overall economic activity. As the chart above shows, data center construction spending, not including the hardware inside, has risen sharply since the launch of ChatGPT in late 2022. The Census Bureau estimates it has reached $96 billion on an annualized basis, well above the roughly $49 billion spent on all other office construction.2 This buildout is one reason the gross private domestic investment component of Gross Domestic Product (GDP), which measures business spending on structures, equipment, and more, accelerated to 3.3% in the third quarter, according to the Bureau of Economic Analysis.3
It is important to distinguish between the potential long-term benefits of AI that many are anticipating, such as productivity gains, improved profit margins, and new business models, and what is currently driving AI-related trends. At present, it is the physical construction of infrastructure that has been propelling economic activity and financial markets in the AI space.
This is reminiscent of the railroad boom of the 19th century, where laying rail lines created jobs and demand for steel and other materials, separate from the longer-term economic gains that faster transportation eventually delivered to the broader economy. Restrictions on data centers may affect the pace of construction activity, but whether AI applications truly boost productivity and generate real economic benefits will ultimately determine the longer-term trajectory of AI adoption.
Technology and AI stocks can be volatile
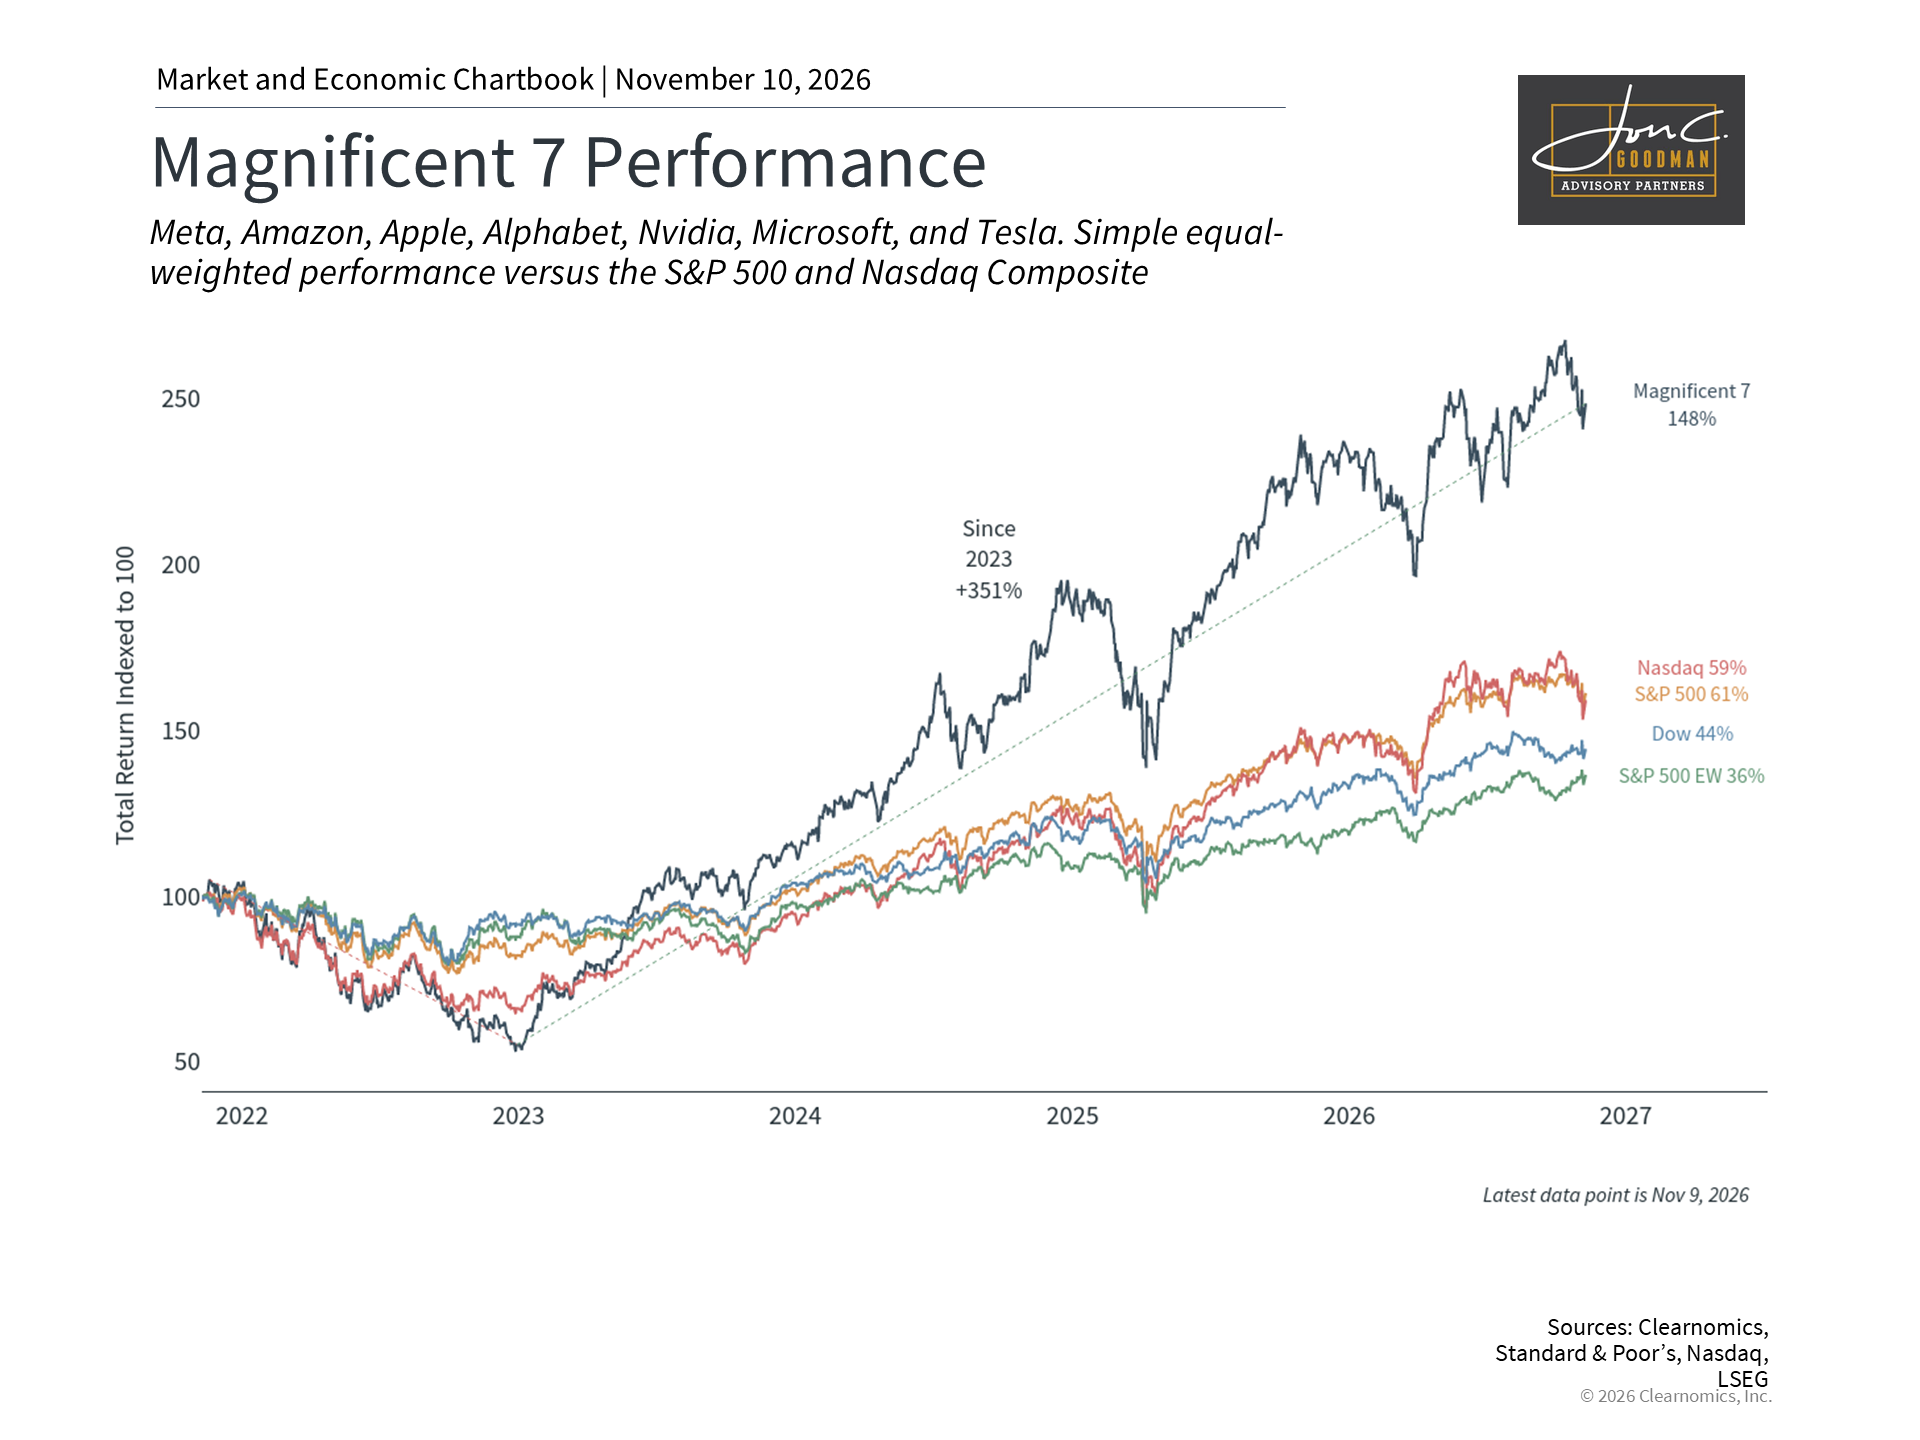
As the chart illustrates, the Magnificent 7 group of technology stocks, which includes Meta, Amazon, Apple, Alphabet, Nvidia, Microsoft, and Tesla, has generated strong returns over the past several years. These stocks have gained around 140% since 2022 and rose about 340% from the start of 2023 to their recent peak, outpacing both the S&P 500 and the Nasdaq.4 At the same time, the chart also highlights significant pullbacks along the way, including the current period of volatility.
The market’s reaction has not been uniform across AI-related companies. Semiconductor manufacturers and so-called “neoclouds,” which are newer public companies providing cloud computing services, experienced sharper declines in the days following the election. By contrast, large “hyperscalers,” the companies funding the AI buildout, did not see their share prices pull back as sharply, though they have faced stress due to concerns over their cash flows.
Pullbacks of this nature are not unusual, even for companies with strong long-term fundamentals. In 2022, when interest rates rose rapidly, the Magnificent 7 declined by nearly 50% before recovering and generating healthy returns for long-term investors. More broadly, transformational technologies have often encountered public and regulatory resistance during their buildout phases.
Of course, today’s volatility also reflects genuine uncertainty. It remains unclear whether new restrictions will prove widespread and lasting, or whether economic incentives will lead many communities to support data center development over time. For investors, this is a reminder that AI does not represent a single investment, but rather a long-term theme with the potential to support portfolios over time.
The bottom line? The midterm election has raised new questions about the pace of data center construction across the country. However, recent volatility is not unusual, and maintaining a long-term perspective with a well-balanced portfolio remains the best way to navigate these periods.
References
- Clearnomics research using Ballotpedia data, as of November 3, 2026
- Clearnomics research using Census Bureau data, as of November 6, 2026
- https://www.bea.gov/news/2026/gdp-advance-estimate-3rd-quarter-2026
- Clearnomics research using Standard and Poor’s, Nasdaq, and LSEG data, as of November 6, 2026
A January Plan for Your Greatest Asset
You wouldn’t let a portfolio drift for months and hope it sorted itself out. Yet that’s what most of us do with our brains every holiday season. The calendar fills up and the to-do list never ends. Late nights, extra sugar and skipped workouts pile up. By January you’re running on fumes, foggy and wondering where your focus went.
Here’s the thing. Your brain isn’t failing you. It’s overloaded. It’s also the CEO of your life. Every decision about your family, your work and your money runs through it and like any good investment, it responds to consistent deposits over time. Your brain loves a plan it can count on. Make yours now and you get to enjoy every moment of the season, knowing clarity is waiting for you in January.
That’s why I created The 5-Day Brain Fog Reset. Everything is laid out for you, so your energy goes into the habits that move the needle.
What you get:
- Five days of meals and a grocery list, with dinners that take 30 minutes or less of hands-on time
- A step-by-step 5-minute morning routine and 5-minute evening wind-down
- 30 minutes of daily movement that works for you
- Guided support from me in our private group chat plus daily emails
- A live Zoom check-in halfway through
- Your before and after Clarity Check-In, so you can see the change
How it works:
- Saturday, January 9: your reset opens. Peek inside and get comfy.
- Sunday, January 10: Prep Day. Shop, chop and stock your fridge for the week.
- Monday to Friday, January 11 to 15: about an hour a day, plus some meal prep
Picture the second week of January. You sit down to a decision that matters and you feel focused. You skip the second coffee. You still have energy at the end of the day for the people you love. Think of it as the rebalance your brain has been waiting for.
Bring your spouse or a friend. Brain health is better together and a reset buddy makes it stick.
Early Bird price: $67 (regularly $97), through November 30 only. Grab your spot at thewellnessnavigator.com/brain-fog-reset.
Aging well isn’t luck, it’s a strategy. What’s yours?
Be well,
Christine Despres
RN, NBC-HWC, CDP, Brain & Metabolic Health Coach