Greetings!
August has a way of sharpening our focus. Summer begins to give way to new routines, markets continue to test investors’ resolve, and many of us find ourselves asking whether we’re spending our time, energy, and resources on what matters most.
This week’s edition explores that very idea from two complementary perspectives.
In Wealth Advisory, we unpack July’s market turbulence—from AI uncertainty and rising Treasury yields to geopolitical tensions and a shifting Federal Reserve. While the headlines may feel unsettling, history reminds us that disciplined investors are often rewarded not by predicting the next headline, but by remaining patient through them.
Then, in Wellness Navigator, Christine Despres transports us to the world’s renowned Blue Zones, where longevity isn’t built on miracle cures, but on simple, sustainable habits practiced every day. Her practical insights offer an encouraging reminder that living well is less about doing more and more about doing the right things consistently.
Whether your goal is building wealth, protecting your health, or simply becoming a little wiser with each passing season, I hope you’ll find something this week that informs, encourages, and inspires.
As always, thank you for spending a few minutes with us. If you find value in what you read, we’d be grateful if you’d share Advice for the Good Life with a friend or family member and encourage them to subscribe. Our mission remains simple: helping people pursue lives that are happier, healthier, wealthier, and wiser.
Until next week,
Wealth Advisory: Navigating AI Uncertainty, High Yields, and Geopolitical Risk
July proved to be a challenging month for financial markets, with major indices finishing slightly in the red. That said, this modest pullback should be viewed in the context of solid year-to-date gains and a broad market that remains near its all-time high. Several forces shaped daily market movements throughout the month, including fresh concerns about AI spending, Treasury yields pushing toward multi-year highs, rising oil prices following a breakdown in the Middle East ceasefire, and the Federal Reserve opting to hold rates steady.
Many of these developments reflect longer-term trends that may continue to generate volatility in the months ahead. At the same time, these very same themes have helped propel markets forward this year, underscoring the value of portfolio balance and a long-term outlook. What takeaways can investors draw from July as they look toward the rest of 2026?
Key Market and Economic Drivers in July
- The S&P 500 and Nasdaq declined -0.1% and -3.2%, respectively, while the Dow Jones Industrial Average rose 0.3% in July.
- Volatility jumped in the middle of the month with the VIX index climbing as high as 21 before settling back toward 16.
- International developed markets returned 1.9% based on the MSCI EAFE Index in U.S. dollar terms, while emerging markets fell -3.3% based on the MSCI EM Index.
- The 30-year Treasury yield surged to a 19-year high to close around 5.28% and the 10-year Treasury yield ended the month at a peak of 4.74%. The Bloomberg U.S. Aggregate Index fell -1.3%.
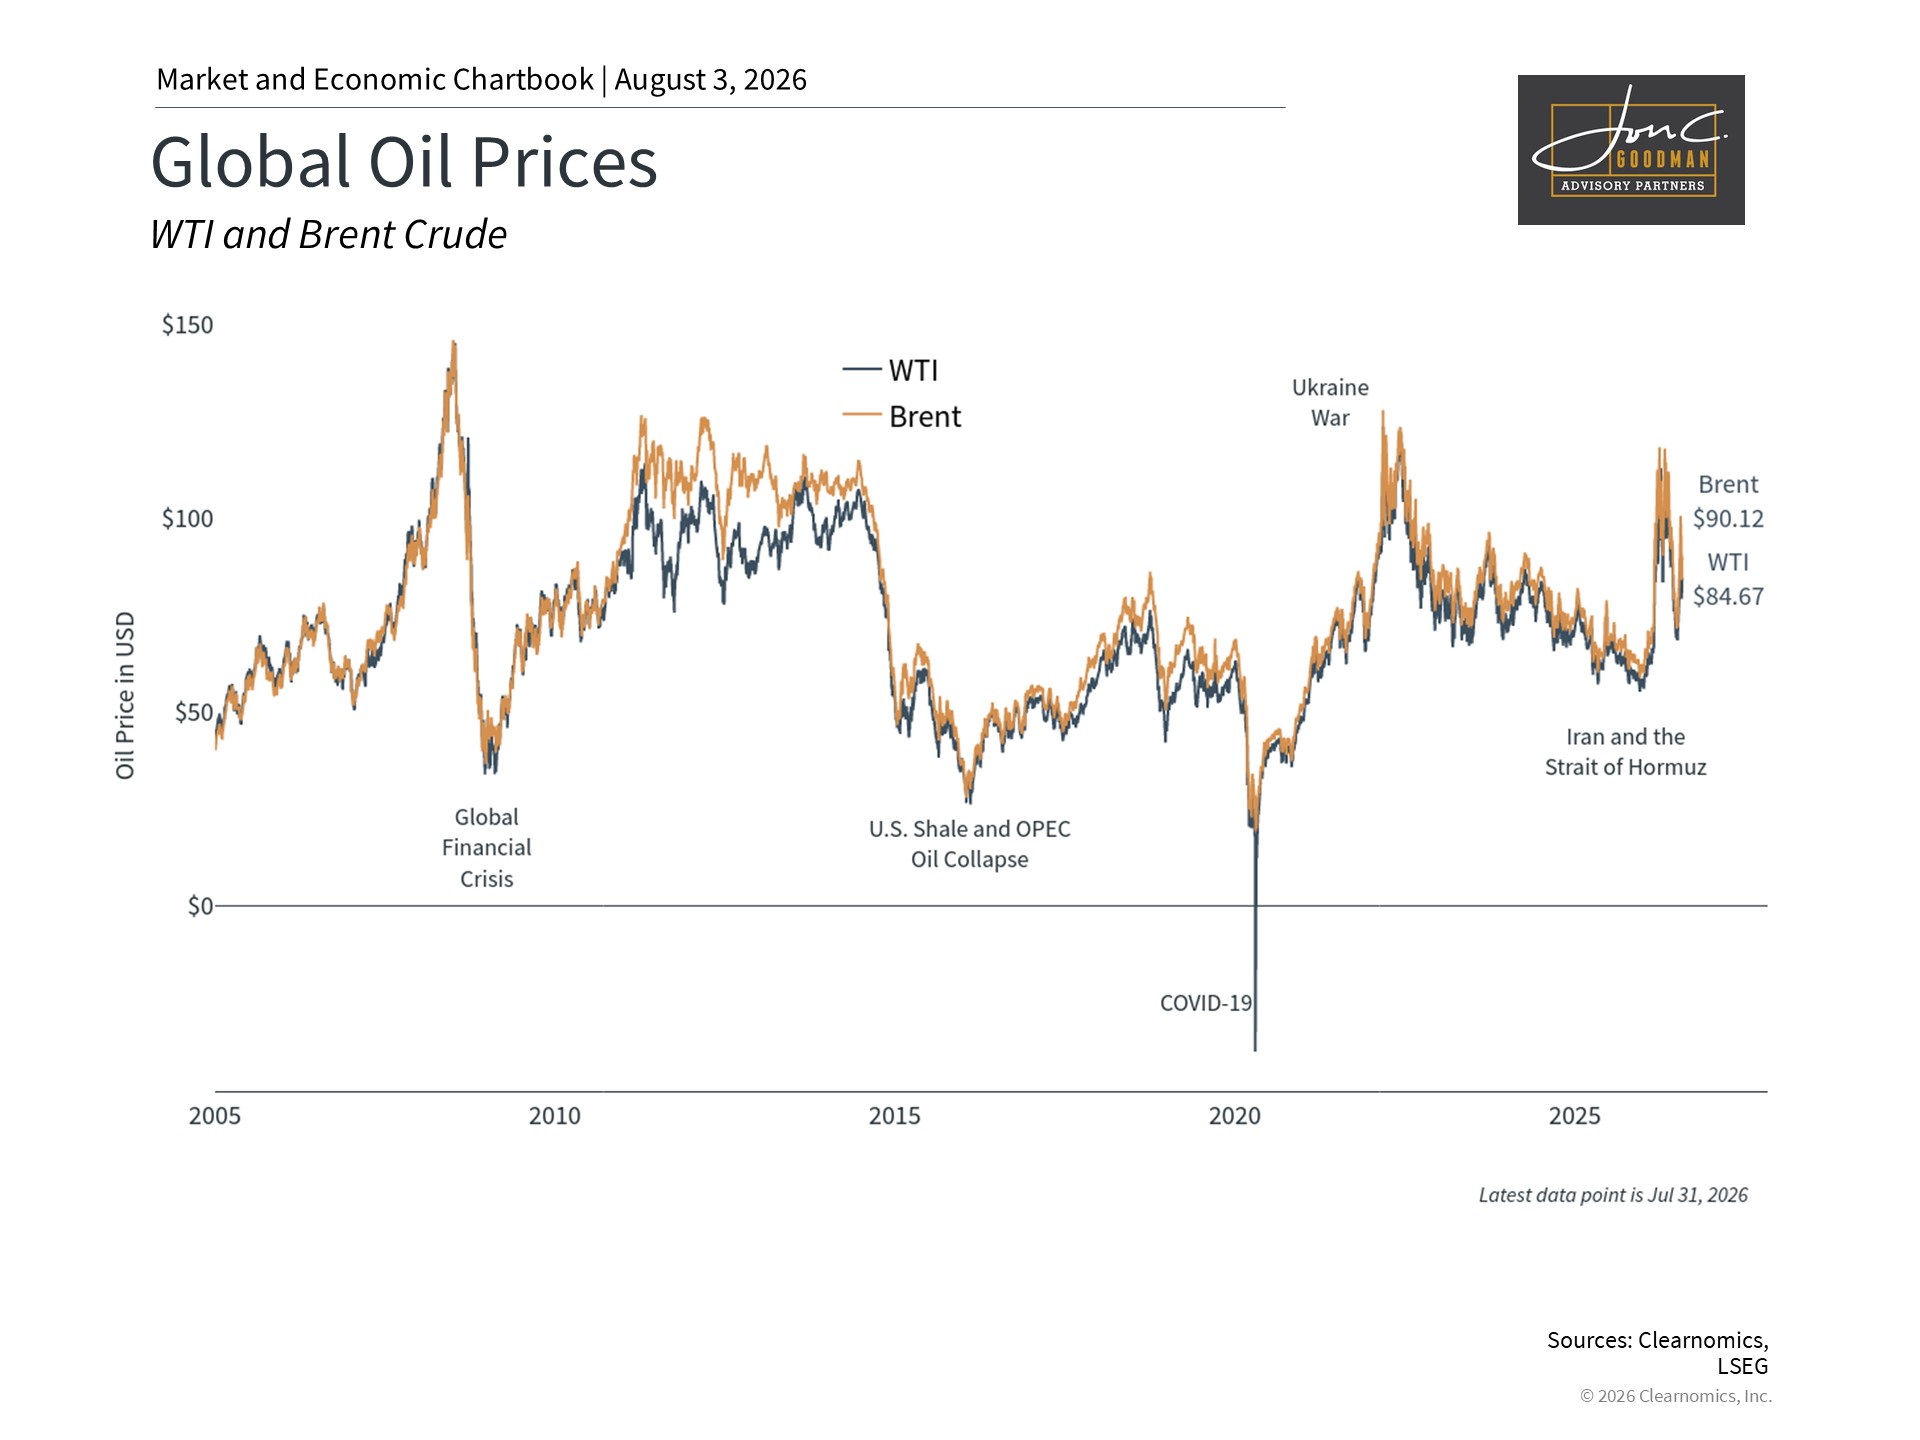
- Oil prices rose with Brent crude climbing above $100 before closing at $90 per barrel and WTI at $85 per barrel.
- The U.S. Dollar Index (DXY) fell just under 100 while the Japanese Yen depreciated significantly, closing around 157. Gold ended the month approximately unchanged at about $4,050 per ounce.
- Second quarter real GDP growth increased at an annual rate of 1.5%, down from the 2.1% growth recorded in the first quarter of the year.
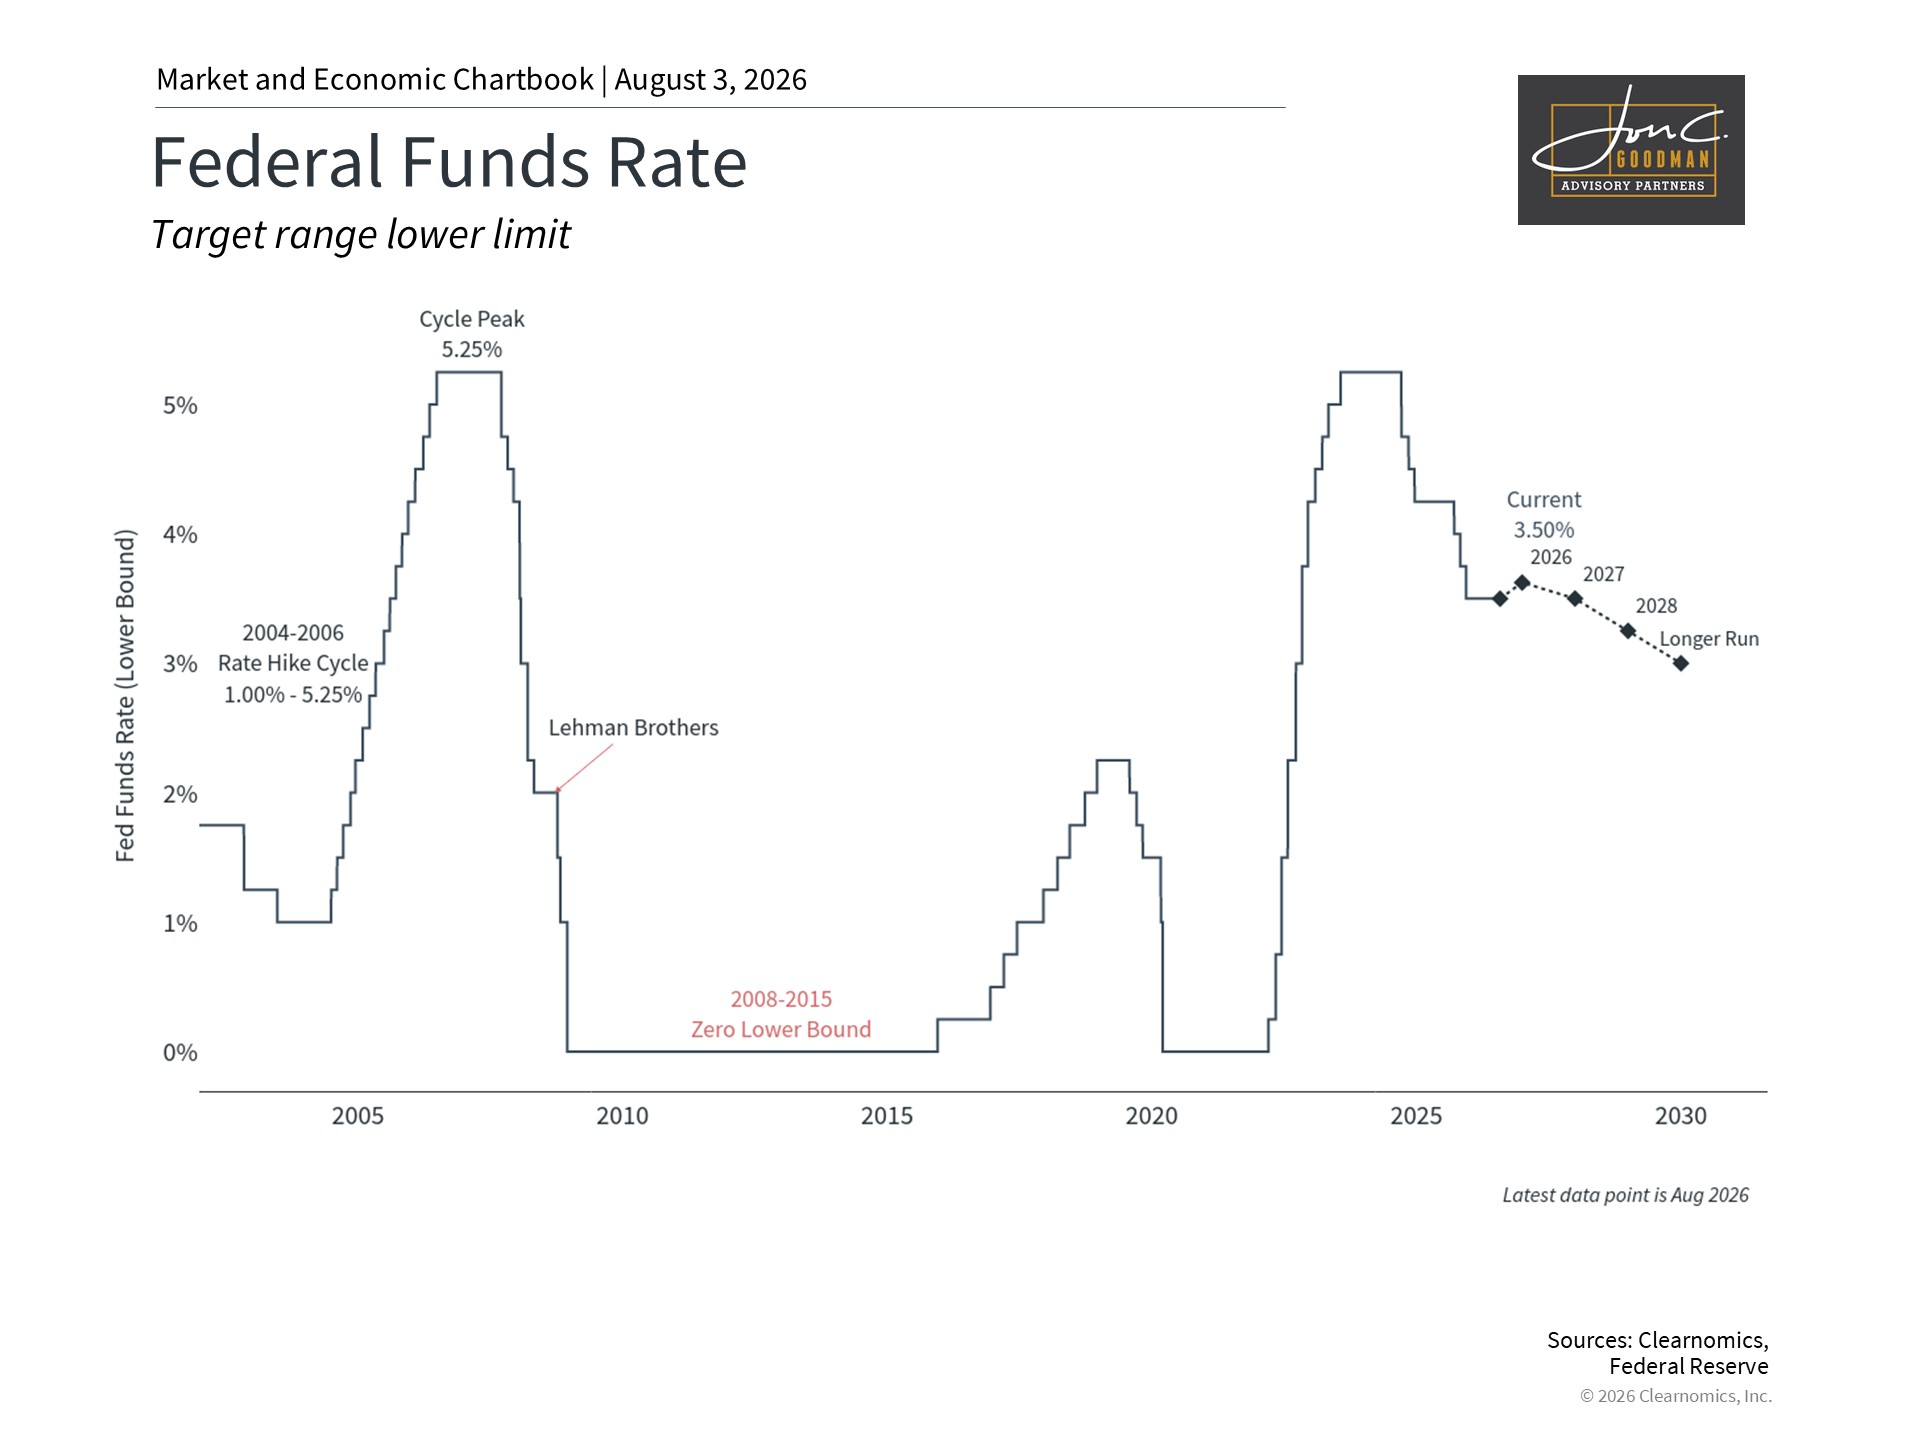
- At the July FOMC meeting, the Federal Reserve decided to keep rates unchanged at 3.50%-3.75% in a 9-3 vote.
AI investment generates mixed signals across the technology sector
Second-quarter corporate earnings reports brought renewed scrutiny to AI-related spending. Market swings during the month largely reflected investor concerns about the free cash flow of large technology companies, commonly referred to as “hyperscalers.” These firms continue to commit hundreds of billions of dollars to new data centers and AI infrastructure, and the market is carefully assessing whether such substantial capital expenditures will ultimately translate into profits. Notably, data center spending alone has grown to become a meaningful contributor to U.S. economic activity, surpassing all other categories of office construction.1
Concerns about this level of investment also rippled through international markets, particularly among global semiconductor companies. Major chip suppliers experienced sharp corrections during the month, contributing to the South Korean KOSPI 200 index falling 24% in July, following a significant run up in 2025. While AI remains a powerful theme driving markets, it also comes with periods of notable volatility.
Another notable AI development in July was the release of a new large language model, Kimi K3, by the Chinese company Moonshot AI.2 This model reportedly competes with the most advanced models from companies such as OpenAI, Anthropic, and Alphabet. It is also “open weight,” meaning that anyone with the right hardware can run the model themselves, in contrast to most frontier models which are proprietary.
Where last year’s DeepSeek models demonstrated that AI could be developed more efficiently, Kimi K3 signals that newer open models can rival cutting-edge proprietary ones. This introduces additional uncertainty about the trajectory of the AI industry, encompassing both hardware and infrastructure requirements, as well as which country will lead the next phase of AI advancement.
Separately, Fitch, the credit rating agency, flagged what it described as “major credit risk” across the AI ecosystem. Their report cited slowing consumer momentum and the highly interconnected nature of financing and supply arrangements among major players.3
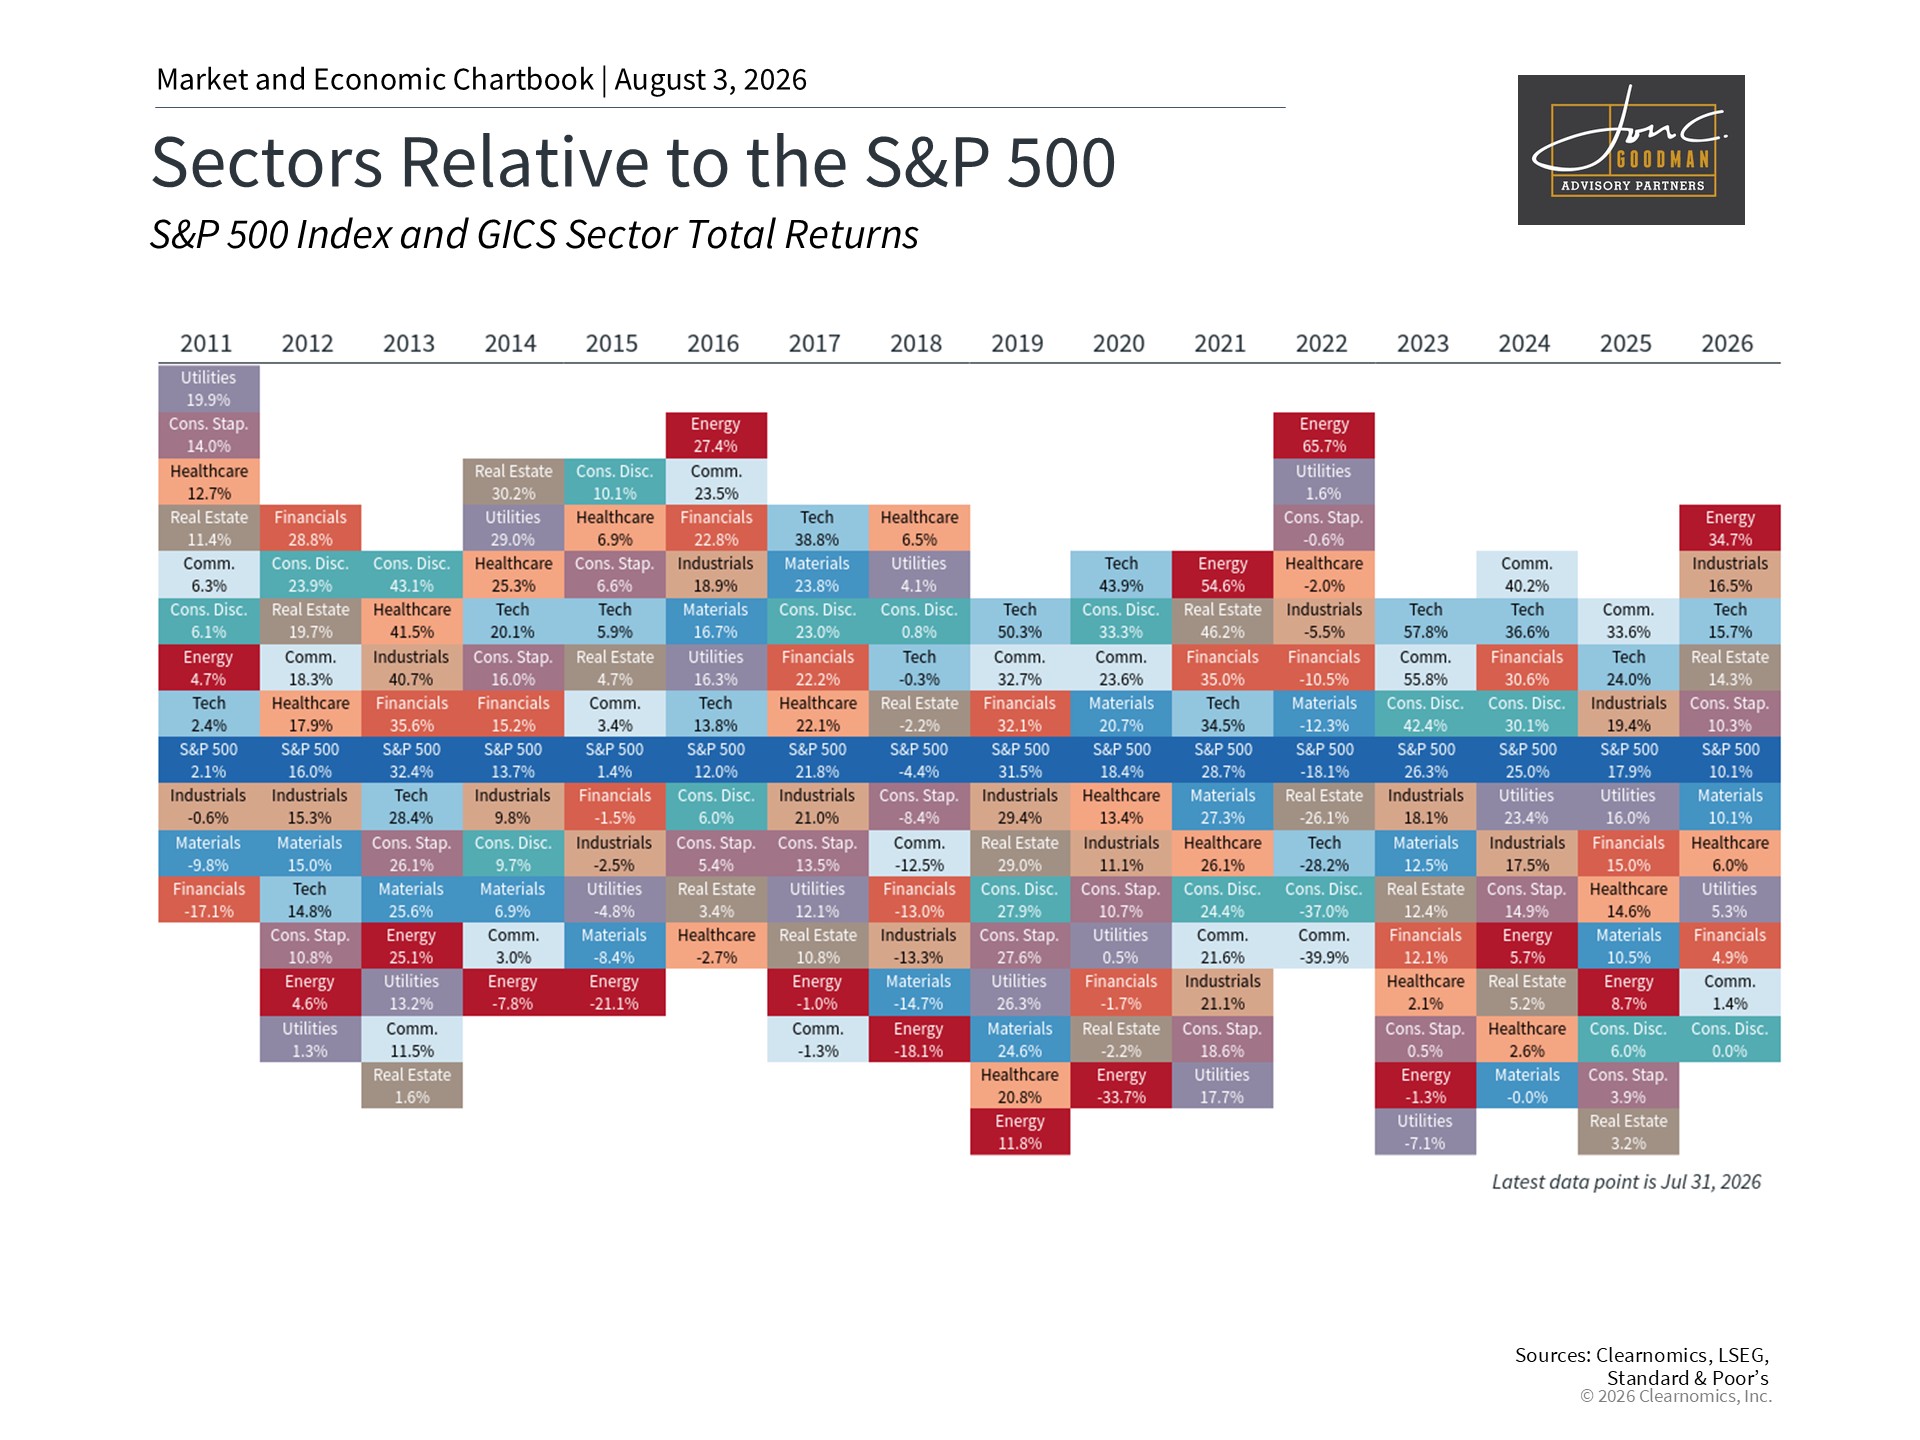
For long-term investors, it is worth remembering that AI is only one of several themes shaping market performance. As shown in the chart above, other sectors have also performed well this year, including Energy, Industrials, and more. While markets will continue to assess the long-term economic impact of AI, maintaining balance across sectors and asset classes remains a sound approach.
Middle East conflict briefly pushes oil back above $100
The ongoing conflict in Iran also contributed to short-term market movements. Tensions flared mid-month when the U.S. carried out additional airstrikes against Iranian military sites, leading to disruptions in traffic through the Strait of Hormuz, a critical chokepoint for global oil supply. The conflict widened further when the Bab al-Mandeb Strait in the Red Sea came under threat after Yemen’s Houthi forces struck Saudi Arabian oil tankers.4
In response, Brent crude briefly surpassed $100 per barrel before retreating to approximately $90 by month-end. For context, oil had fallen as low as $72 per barrel earlier in July. Elevated energy prices carry broader economic implications, as they directly increase fuel costs for households and businesses. Gasoline prices remain around $4.10 per gallon nationwide, a level that could keep headline inflation elevated.5
Federal Reserve holds rates steady amid a divided committee
At its July meeting, the Federal Open Market Committee (FOMC) kept the federal funds rate unchanged within a range of 3.50% to 3.75%, despite ongoing concerns about inflation.6 This decision sparked additional market volatility as bond yields moved higher and investors worked to assess the timing of any potential future rate increases.
New Fed Chair Kevin Warsh has deliberately scaled back communication about how the Fed might act at future meetings. The FOMC statement has been simplified considerably, and Warsh has declined to answer questions about how the Fed might respond to various economic scenarios. This reduction in “forward guidance” leaves investors less certain about how the Fed would react to higher inflation, a weakening labor market, or other shifting conditions.
The immediate market reaction was a rise in bond yields, with both nominal and real Treasury rates climbing to their highest levels in recent years. Market-based expectations now suggest the Fed could raise rates once by October, and possibly twice by mid-2027.
Adding to the intrigue, three Fed officials dissented at the latest meeting, indicating they preferred a rate increase. This degree of internal disagreement has been uncommon in recent years, with the last comparable instance occurring in September 2016. For markets, this level of dissent offers a window into what the Fed may be weighing at upcoming meetings, particularly if inflation remains elevated.
For investors, uncertainty around Fed policy could translate into greater yield volatility. At the same time, higher yields present opportunities for meaningful portfolio diversification.
New tariffs add more economic uncertainty
New tariffs introduced additional complexity to the economic backdrop in July. After the Supreme Court ruled that last year’s reciprocal tariffs under the International Emergency Economic Powers Act were illegal, the administration responded by implementing new tariffs under a different trade law, Section 122 of the Trade Act of 1974. Those tariffs expired in July, prompting the White House to implement further tariffs under different trade rules.
The net result is that many countries now face tariffs ranging from 10% to 12.5%. Certain countries face considerably higher rates, including a 50% tariff on specific Canadian goods such as cement, dairy, and alcohol. These tariffs were implemented under Section 338 of the Tariff Act of 1930, citing what the administration described as discriminatory treatment of American products.7
As always, the full economic effects of these tariff measures will take time to materialize. A key consideration for long-term investors is that many of the market and economic concerns stemming from tariffs have not unfolded as some had feared. While tariffs do affect specific industries and consumer prices, companies can adapt and adjust their pricing strategies over time. In fact, the economy has grown steadily and the S&P 500 has reached many new all-time highs over the past year.
The bottom line? July reinforced the importance of keeping a long-term perspective. Market challenges can create opportunities for investors who are positioned across different asset classes. Staying focused on the bigger picture, rather than reacting to the news headlines, remains the best way to achieve financial goals.
References
- https://www.census.gov/construction/c30/c30index.html
- https://forum.moonshot.ai/t/kimi-k3-is-here-our-most-capable-model/480
- https://www.fitchratings.com/research/banks/ai-market-correction-emerging-as-major-credit-risk-27-07-2026
- https://apnews.com/article/yemen-saudi-houthis-attack-shipping-red-sea-4e25fbdad821762e478173e6308884fb
- https://gasprices.aaa.com/
- https://www.federalreserve.gov/newsevents/pressreleases/monetary20260729a.htm
- https://www.whitehouse.gov/fact-sheets/2026/07/fact-sheet-president-donald-j-trump-imposes-additional-tariffs-on-canada/
Wellness Navigator and Holistic Brain Health Coach, RN, NBC-HWC, CDP
Lessons from the Blue Zones We Can Take Home
I can’t believe it’s already August and everyone’s talking about back to school, because I am nowhere near done reliving my trip to Italy. I keep mentioning the Blue Zones in conversation and I’m always surprised by how many people haven’t heard of them.
The Blue Zones are five regions around the world where people live measurably longer, healthier lives, not because of a supplement or a strict diet, but because of how daily life is built. Sardinia is one of the five, and it’s next on my Italian wish list. I didn’t make it there this trip, but everything I read about it makes me want to go even more.
In 1990, the average person spent 8.8 years of life in poor health. By 2023, that climbed to 10.7 years, a 22 percent increase. More medical care is keeping people alive longer but not necessarily living better. Here’s the part I want you to sit with. The power to age well lies within your lifestyle and habits, more than you might know.
So what can we actually take home from this?
Here are my five top takeaways:
1-Move with purpose every day, all day. This isn’t about a scheduled workout, it’s about staying in motion throughout the day, walking, standing, doing tasks that get your body moving. Regular movement supports the growth of new brain cells and helps protect memory over the long term.
2-Cook real food. Whole ingredients, prepared with intention, support better blood sugar regulation and lower inflammation, and inflammation is one of the biggest drivers of cognitive decline.
3-Share meals with others. Eating with someone else, not alone or on the go, activates the same social connection that lowers chronic stress, and chronic stress is one of the things that wears down memory over time.
4-Stay open. Trying new things, whether it’s a recipe, a class, or a new conversation, builds resilience. Novelty keeps your brain actively engaged instead of running on autopilot, and that ongoing engagement is part of what protects cognitive function as you age.
5-Protect your social connections. Strong relationships aren’t just emotionally satisfying, they’re neuroprotective. Real, regular connection has been linked to lower rates of cognitive decline over the long term.
Does this sound familiar? I talk about these principles a lot and for good reason.
There’s so much information out there about how to live well and age well and it can feel overwhelming to know where to start. That’s exactly what I help with in coaching, cutting through the noise and getting straight to what’s scientifically proven to move the needle for you.
There’s still time to sign up for the Brain Boost Session this month.
It’s a brain health experience to help you think clearly, feel better and thrive. We’ll do a short guided meditation, break down the science on aging and brain function, and walk through simple, actionable strategies you can use right away, all in a relaxed, no pressure space.
It’s the first Wednesday of every month, 10am ET. Sessions are recorded.
Save your spot here: https://www.thewellnessnavigator.com/free-brain-boost-sessions
Here’s to living healthier, not just longer,
Christine